Guides
Gambling wins and the tax office
Australian punters are often told that gambling winnings are tax-free, and for most people that holds. We went to the ATO's own guidance and rulings, and to the court decisions they rest on, to set out where the rule comes from, when it stops applying, what happens to interest earned on a win, and how the tax burden falls on operators instead.
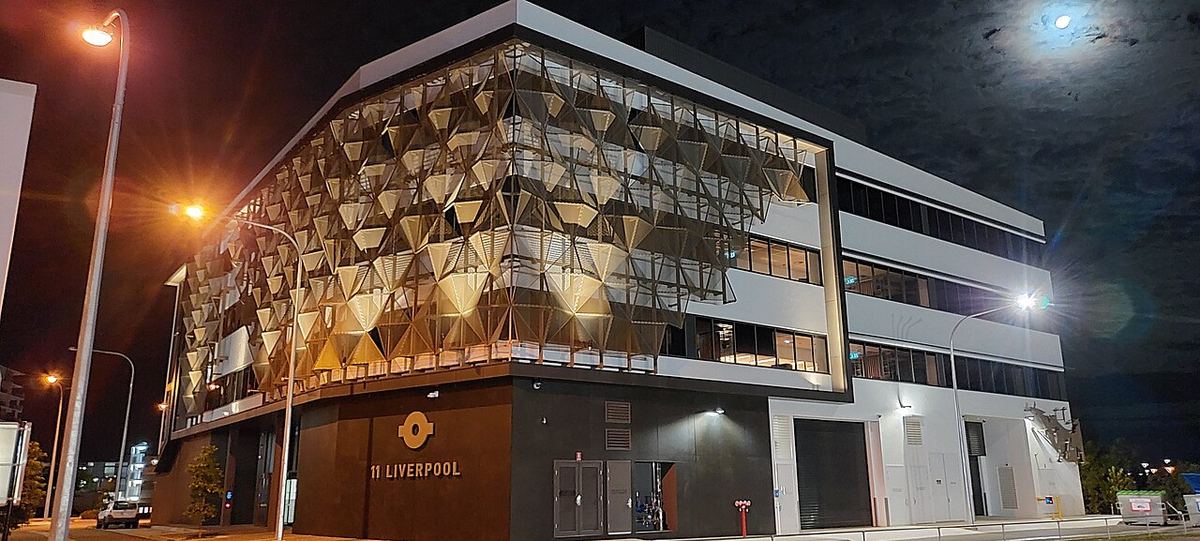
The Australian Taxation Office building in Townsville, opened in 2020. Photo: Greditdesu, CC BY-SA 4.0
On this page 8 sections
Are gambling winnings taxed in Australia?
For a recreational punter, no. The ATO's guidance on income to exclude lists "betting and gambling wins (unless you operate a betting or gambling business)" among amounts that are not assessable. A collect on the races, a payout from a pokie or a win at the casino table is not income in the tax sense for most people, and it does not go on a tax return.
The flip side matters just as much. Because the wins are not income, the losses are not deductions. A punter who loses $10,000 over a year cannot claim it against wages, any more than a punter who wins $10,000 has to declare it.
What about lotto, raffles and game shows?
The ATO's instructions for question 24, Other income, tell taxpayers: "Don't include prizes won in ordinary lotteries, for example, lotto draws, caskets and raffles." Game show prizes are also left out, unless you regularly received appearance fees or game show winnings. The exception is a benefit or prize from an investment-related lottery, which is included. In practice, a Powerball or Saturday Lotto win is treated like any other gambling win.
Can I claim my gambling losses?
Only if the gambling is a business. The ATO's ruling IT 2655, issued after three Federal Court decisions in 1989, states plainly: "There is no Australian case in which the winnings of a mere punter have been held to be assessable (or the losses deductible)." Winnings and losses sit on the same side of the line. If one is outside the tax system, so is the other.
When does gambling become a business?
This is the question the 1989 cases answered. IT 2655 draws on them to list the factors that point towards a business of gambling:
- Whether the betting is conducted in a systematic, organised and businesslike way;
- The scale of the activity;
- Whether the gambling is connected with other businesslike activities, such as horse breeding;
- Whether the main aim is profit or pleasure;
- Whether the form of gambling turns on skill and judgment or on chance;
- Whether it looks more like a hobby or pastime.
No single factor decides it. The cases show how high the bar sits. A review of the three decisions in the Revenue Law Journal describes them this way:
- Evans v FCT (1989) 89 ATC 4540. Hill J accepted that Evans had largely lived off his gambling wins, yet he was not carrying on a business, because his betting lacked system and organisation. He did not use a computer, keep an office or study the form extensively.
- Babka v FCT (1989) 89 ATC 4963. A retired public servant kept meticulous records of his betting. Hill J held that a pastime does not become a business merely because the person has retired.
- Brajkovich v FCT (1989) 89 ATC 5227. The taxpayer retired at 36 to gamble, owned racehorses, bet on credit, played cards and two-up, and wanted to deduct his losses. The Full Federal Court set out the criteria above and held that he was not in business. In the court's words, gambling "unconnected with what might ordinarily be described as commercial activity, has no tax implications unless it is or is an aspect of, a business".
The same review contrasts these with Trautwein (1936) 56 CLR 196, where a stud farm owner who bet systematically using valuable racing information was taxed. A business finding tends to follow a commercial setting around the betting, not just large sums. Our piece on gambling as a profession in Australia looks at the day-to-day side of that life; the tax test is narrower than most people assume.
Does betting big change anything?
Not on its own. Scale is one factor among several, and Brajkovich bet heavily without being found to run a business. The size of a bet is not what makes a punter taxable; the way the whole activity is organised is.
Do I pay tax on interest earned from a win?
Yes. The win itself is not income, but what it earns afterwards is. The ATO's page on investment income says: "If you're an Australian resident and you receive interest, you must declare it as income." It goes in the gross interest item on a paper return or the interest section in myTax.
A worked illustration, using an interest rate we have picked only to show the arithmetic: a punter banks a $200,000 win in an account paying 4% a year.
- The $200,000 win: not declared.
- Interest for the year: $200,000 × 4% = $8,000.
- The $8,000 is declared as interest income and taxed at the punter's marginal rate.
The same applies to dividends from shares bought with winnings, or rent from a property bought with them. The source of the capital is irrelevant once it starts producing income.
So who pays tax on gambling?
Operators do. States tax wagering operators on bets placed by their residents through a point of consumption tax. We confirmed the rates for three states:
- New South Wales: 15% of net wagering revenue from NSW customers above a $1,000,000 threshold, a rate in place from 1 July 2022 under s 13C of the Betting Tax Act 2001, according to Revenue NSW.
- Victoria: 15% of net wagering revenue, including GST, above $1,000,000, for the period 1 July 2024 to 30 June 2027, under the Gambling Taxation Act 2023, according to the State Revenue Office Victoria.
- Queensland: 20% above an annual threshold of $300,000, according to Queensland Revenue Office.
To see the scale, take an operator with $5,000,000 of net wagering revenue from NSW customers in a year: ($5,000,000 − $1,000,000) × 15% = $600,000 in tax. The same revenue from Queensland customers would give ($5,000,000 − $300,000) × 20% = $940,000. Punters never see these amounts on a bet slip; our explainer on reading betting odds shows where the bookmaker's margin sits in the prices.
What about winnings from overseas?
This is where other countries' rules come in, strictly as a contrast. The ATO guidance quoted above does not draw a line based on where a bet is placed; for an Australian recreational punter, the business test is what matters. Other countries may tax gambling wins under their own law, and that is a question for the law of the country where the win happens. We do not set out foreign rules here. Separately, an online casino offering its games to Australians from offshore is not a lawful Australian service, as our summary of Australian gambling law explains.
Checklist before you think about tax
- Recreational win from racing, sports, pokies, casino games or lotto: not declared, losses not claimed.
- Prize from an investment-related lottery: included as other income.
- Regular game show appearance fees or winnings: included.
- Interest, dividends or rent earned on winnings: declared like any other investment income.
- Betting that is systematic, large-scale, profit-driven and tied to a commercial activity: get advice, because the business test may apply.
- Records of large wins: worth keeping, to show where money in your account came from.
Treating gambling as a source of income is also a warning sign in its own right. If betting has started to feel like something you need to win at, Gambling Help Online offers free counselling on 1800 858 858, and you can exclude yourself from licensed online wagering through BetStop, the National Self-Exclusion Register. Our responsible gambling page has more options. Gambling is for adults 18 and over.
Sources
- ATO: What income to exclude (business assessable income)
- ATO: Supplementary tax return 2026, question 24 Other income
- ATO: Taxation Ruling IT 2655, gambling and betting
- ATO: Investment income you must declare
- Revenue Law Journal (Bond University): review of Evans, Babka and Brajkovich
- Revenue NSW: Point of consumption tax
- State Revenue Office Victoria: Wagering and betting tax current rates
- Queensland Revenue Office: Betting tax rate and threshold
Frequently asked questions
Do I have to declare a lotto win to the ATO?
No. The ATO's instructions for question 24 say not to include prizes won in ordinary lotteries such as lotto draws, caskets and raffles.
Are professional gamblers taxed in Australia?
Only if their gambling amounts to a business. The courts have set a high bar, and the ATO says there is no Australian case in which a mere punter's winnings were held assessable.
Is interest on gambling winnings taxable?
Yes. The win is not income, but the ATO requires Australian residents to declare interest they receive, including interest earned on banked winnings.
Can I deduct gambling losses from my income?
Not as a recreational punter. Because the winnings are not assessable, the losses are not deductible unless the gambling is a business.
Read next
 Betting MathsInstant Scratchies Odds: What a Ticket Returns on AverageThe odds printed on a scratchie count every prize, including the ones that only hand your stake back. We run the numbers on three published prize…
 Betting MathsKeno Odds by Number of Spots, Worked OutHow likely is a full catch on a 10-spot, and what does the prize table actually hand back per dollar? We calculated the odds for every spot size from…
 PokiesLightning Link and Dragon Link: How the Games WorkLightning Link and Dragon Link fill gaming rooms across the country, yet few punters know what the link actually is. We go through the Hold & Spin…
18+Order set by our editors; we earn a commission on sign-ups through partner links — how this works. Decide your budget and session time before you start.